
What if selling a big block of stock all at once is the fastest way to hand your gains to the IRS?
If you’re about to realize a large gain, timing, managing tax brackets, loss harvesting, and smart charitable moves can save you thousands, sometimes much more.
This post lays out a clear, step-by-step plan to split sales across years, harvest losses, and donate or use a donor-advised fund so you keep more of your money.
Act before you hit sell; tax choices are mostly decided before settlement.
Core Strategies to Reduce Taxes on a Large Stock Sale
Planning a large stock sale means making choices that keep more of your gain. The tactics that work best combine timing, bracket management, loss offsetting, and charitable strategies. Most taxpayers can cut their tax bill by thousands or even hundreds of thousands by stacking these methods before they press “sell.”
Every dollar of capital gains tax you avoid is a dollar you keep. You need to act before the sale closes. Once the transaction settles in your brokerage account, the tax is locked in for that year.
• Harvest capital losses from other positions to offset realized gains dollar for dollar before selling your winner.
• Split the sale across multiple tax years to avoid pushing all income into a single year and triggering higher brackets or the 3.8% Net Investment Income Tax.
• Donate appreciated shares directly to charity to eliminate capital gains tax and claim a fair market value deduction if you itemize.
• Use a donor advised fund to bunch several years of charitable giving into one tax year, shelter a large block of stock from gains, and retain flexibility on when grants go out.
• Maximize long term capital gains treatment by holding positions longer than one year to access the 0%, 15%, or 20% rates instead of ordinary income rates up to 37%.
• Review state residency rules if relocating to a no tax or lower tax state before the sale can materially change your after tax proceeds.
Timing matters most when your income varies. If you expect a lean year (retirement, sabbatical, or a gap between jobs), realizing gains during that window can keep you in the 0% or 15% long term capital gains bracket. Loss harvesting works best late in the year when you know your total gains and can fine tune offsets. Charitable strategies deliver the largest benefit when you bunch multiple years of donations into the year of a large liquidity event. Coordinate all these moves with your tax professional before December 31 of the sale year.
Understanding Capital Gains Taxes for Large Stock Sales
Short term capital gains apply to stock you held one year or less. The IRS taxes those gains as ordinary income, using the same rate schedule as your salary or freelance income. That means rates from 10% up to 37% depending on your total taxable income. If you sell a concentrated position after holding it for only eight months, every dollar of profit gets taxed at your marginal ordinary rate.
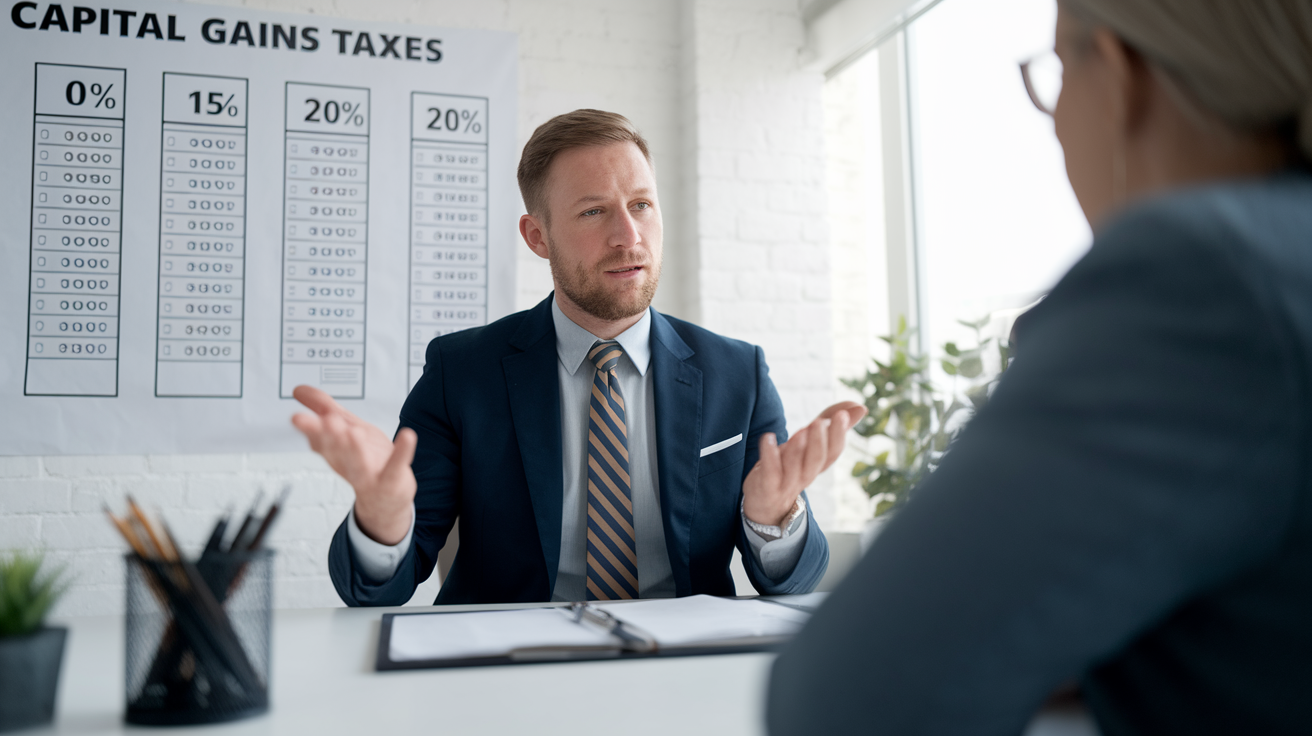
Long term capital gains apply when you hold stock for more than one year. The federal tax rate drops to 0%, 15%, or 20%, determined by your taxable income. For 2026, married couples filing jointly pay 0% on long term gains if their taxable income stays below $96,700. The 15% rate applies from $96,700 up to $613,700. Above $613,700, the rate jumps to 20%. Single filers face a 0% rate up to $48,350, 15% from $48,350 to $553,850, and 20% above that threshold.
A large one time stock sale can push you from the 15% capital gains bracket into the 20% bracket in a single year. That same sale may also trigger the 3.8% Net Investment Income Tax if your modified adjusted gross income exceeds $250,000 for joint filers or $200,000 for single filers. The combination of a 20% capital gains rate plus the 3.8% surtax means a top federal rate of 23.8% on gains.
Add state capital gains taxes, and the rate can climb above 30% in high tax states like California or New York. Managing when and how much you sell in one tax year directly controls which brackets and surtaxes apply.
Timing Your Stock Sale for Optimal Tax Results
Selling your entire position in one calendar year gives you immediate liquidity but locks in the highest possible tax. Spreading the sale over two or three years lets you control how much taxable income lands in each year, keeping more of your gain in lower brackets and avoiding surtax thresholds. You sacrifice some flexibility and accept market risk while you wait, but the tax savings can be substantial.
Adjusted gross income determines your capital gains bracket, your exposure to the Net Investment Income Tax, and how much of your Social Security benefits gets taxed. A $900,000 gain realized in December 2026 counts entirely in 2026. If you split that same gain ($300,000 in December 2026, $300,000 in January 2027, and $300,000 in January 2028), you spread the income across three tax returns and may stay below the 20% bracket threshold in all three years.
Here’s how to execute a split sale:
Calculate your current year taxable income before any stock sale to see how much room you have in the 0% or 15% long term capital gains brackets. Model a multi year sale schedule that realizes gains up to but not beyond the bracket thresholds in each year, factoring in other income sources like salary, bonuses, or required minimum distributions. Execute the first tranche before December 31 to lock in the current tax year, then wait until January 2 or later for the next tranche to push income into the following year. Track your modified adjusted gross income each year to confirm you stay below NIIT and Medicare premium surcharge thresholds.
The trade off is market exposure. If the stock drops 15% while you wait to sell the second tranche, your tax savings may be wiped out by the price decline. If the stock climbs another 20%, you end up with a larger gain in year two but also a higher tax bill. Only split sales across years if you can accept the risk of price movement or if you hedge the position while you wait.
Using Tax Loss Harvesting to Offset Gains
Tax loss harvesting means selling investments that have lost value to realize a capital loss, which you then use to offset realized capital gains from other sales. Losses offset gains dollar for dollar. If you harvest $50,000 of losses and realize $150,000 of gains in the same year, you only pay tax on the net $100,000 gain. If your losses exceed your gains, you can use up to $3,000 of the excess to reduce ordinary income, and any remaining loss carries forward to future years indefinitely.
The best time to harvest losses is late in the year, after you know your total realized gains and can calculate exactly how much loss you need. Pull up every position in your taxable brokerage account and sort by unrealized loss. Sell the losers you no longer want to hold, or sell and immediately replace them with a similar but not identical investment to maintain your asset allocation. Make sure the replacement is different enough to avoid the wash sale rule.
The wash sale rule disallows a loss if you buy the same security or a substantially identical one within 30 days before or after the sale. If you sell a tech stock at a loss on December 15 and repurchase it on December 20, the IRS disallows the loss and adds it to the cost basis of the new shares. To stay compliant, wait 31 calendar days after the sale before repurchasing, or buy a different stock or ETF in the same sector.
The wash sale rule only applies to losses, not gains, so you can sell a winner and repurchase it the same day without penalty.
Charitable Giving Strategies to Reduce Taxes on a Stock Sale
Donating appreciated stock directly to a qualified charity eliminates capital gains tax on the appreciation and gives you a charitable deduction for the full fair market value if you itemize. The tax benefit is double. You avoid paying tax on the gain, and you reduce your taxable income by the amount of the donation.
• Donate shares you’ve held for more than one year to qualify for the fair market value deduction; shares held one year or less are deductible only at cost basis.
• Transfer shares electronically from your brokerage account to the charity’s brokerage account to preserve the tax benefit; selling first and donating cash triggers capital gains tax.
• Confirm the charity is a 501(c)(3) organization to ensure your donation is deductible.
• Keep documentation including a receipt from the charity and records of the stock’s basis and fair market value on the date of transfer.
• Understand AGI limits: donations of appreciated stock are generally deductible up to 30% of your adjusted gross income in the year of the gift; excess contributions can be carried forward for up to five years.
Charitable giving works best when you plan to make donations anyway and can substitute appreciated stock for cash. If you were going to write a $50,000 check to charity and you own stock with a $50,000 market value and a $10,000 cost basis, donate the stock instead. The charity receives $50,000 (tax free to them), you claim a $50,000 deduction, and you avoid paying capital gains tax on the $40,000 gain.
The math almost always favors donating appreciated shares over cash if you have both available.
How Donor Advised Funds Can Support Large Stock Sale Planning
A donor advised fund is a charitable account that accepts donations of cash or appreciated stock, gives you an immediate tax deduction, and lets you recommend grants to charities over time. You get the tax benefit in the year you contribute, even if the money sits in the fund for years before you direct it to specific nonprofits. This structure is especially useful during a large liquidity event when your income and tax rate spike in one year.
Contribute a block of appreciated stock to a donor advised fund in the same year you sell the rest of your position. The contribution shelters the donated shares from capital gains tax, and the deduction reduces your taxable income in the year of the sale, lowering your overall tax bill and potentially keeping you below surtax thresholds. You retain advisory control over which charities receive grants and when, so you can spread charitable gifts over multiple years while capturing the full tax benefit upfront.
Donor advised funds work best when you want to bunch several years of charitable giving into a single high income year. If you normally donate $20,000 per year and you’re selling a concentrated stock position in 2026, contribute $100,000 of appreciated shares to a donor advised fund in 2026. You claim the full $100,000 deduction in 2026 (subject to AGI limits), and over the next five years you recommend $20,000 annual grants from the fund to your chosen charities.
The upfront deduction offsets the income spike from the stock sale, and you maintain your annual giving pattern without writing checks each year.
Installment Sales and Deferral Techniques
An installment sale spreads the taxable gain from a sale over multiple years by receiving payments over time instead of a lump sum. Each year, you report a portion of the gain based on the ratio of principal received to the total sale price. This method keeps large gains from stacking into a single tax year and can keep you in lower brackets throughout the installment period.
Installment sales work for private company stock, real estate, and some other assets, but publicly traded securities are generally ineligible under IRS rules. If you own stock in a privately held company and negotiate a buyout paid over three years, you can use the installment method to defer recognition of the gain. The buyer pays you in annual installments, and you report the proportional gain each year as you receive cash. The deferred gain remains exposed to changes in tax law, and you take on credit risk if the buyer defaults.
For publicly traded stock, deferral options are more limited. You can split the sale manually across tax years as described earlier, or explore qualified opportunity zone investments if you have realized gains from other sources. Opportunity zones allow you to defer and potentially reduce capital gains by investing sale proceeds into designated low income communities, but the rules are complex, the investment window is time sensitive, and not all stock sale scenarios qualify.
Installment sales are powerful for private transactions, but they require careful structuring, legal documentation, and ongoing compliance. Always model the multi year tax impact and compare it to selling outright before committing to an installment structure.
State Specific Tax Considerations for Large Stock Sales
State income tax on capital gains varies dramatically. Nine states (Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Washington, and Wyoming) have no state income tax on capital gains. California taxes long term capital gains at the same rates as ordinary income, with a top marginal rate of 13.3%. New York’s top rate is 10.9%, and New Jersey’s is 10.75%. The difference in state tax alone on a $1 million gain can exceed $100,000.
Residency determines which state gets to tax your gain. Most states use a combination of physical presence and domicile tests. You must live in the new state for a minimum number of days, change your driver’s license and voter registration, move your financial accounts, and demonstrate intent to make the new state your permanent home. Some states (California and New York especially) audit high income taxpayers who claim to have moved before a large stock sale.
• Establish physical presence by spending more than 183 days per year in the new state.
• Change your domicile by updating legal documents, registering to vote, and filing a declaration of domicile with the new state.
• Close ties to your old state by selling your primary residence, terminating club memberships, and moving personal property.
• Document your move with travel records, credit card statements, and utility bills showing where you actually lived during the year.
If you plan to relocate before selling stock, move at least six months before the sale and spend the entire time in the new state to minimize audit risk. Don’t sell stock while you still own a home in a high tax state or while your family remains there, because the old state may argue you never truly left.
Changing residency purely to avoid taxes is legal, but the move must be real, and the timing must be clear. Model the state tax savings against the cost and disruption of relocating, and consult a tax advisor in both states before you execute the plan.
Final Words
You learned the practical moves: timing sales across years, tax-loss harvesting, donating appreciated shares, using donor-advised funds, and watching state rules.
We also covered long- vs short-term rates, wash-sale limits, installment options, and when each tactic fits a big liquidity event.
Before you sell, gather trade history, run multi-year scenarios, and check the numbers with your CPA.
This checklist gives a clear road map for how to plan a large stock sale to minimize taxes — and puts more of your gains within reach.
FAQ
Q: Is there a way to avoid taxes when selling stock?
A: There are ways to reduce or avoid taxes when selling stock. Common methods include holding for long‑term rates, tax‑loss harvesting, donating appreciated shares, using donor‑advised funds, and spreading sales across years.
Q: What is the 7% rule for selling stocks?
A: The 7% rule is a selling guideline suggesting you consider trimming or rebalancing a position after about a 7% gain or loss to manage risk; it’s a practical rule of thumb, not a tax rule.
Q: How much capital gains tax will I pay on $300,000?
A: The capital gains tax on $300,000 depends on holding period and total income—long‑term rates are 0%, 15%, or 20%, while short‑term gains are taxed as ordinary income; high earners may face the 3.8% NIIT.
Q: What is the 20% rule for capital gains?
A: The 20% rule for capital gains refers to the top federal long‑term capital gains rate of 20% that applies once taxable income exceeds the top threshold; very high incomes may also owe the 3.8% NIIT.

