
Think wash sale rules only matter inside one brokerage? Think again.
A single loss sale can disappear if any account you control—or your spouse controls—buys the same or a substantially identical security (meaning nearly the same investment) within 30 days before or after.
That 61-day window is where most people get burned: IRAs, 401(k)s, dividend reinvestment and automatic buys are the usual traps.
This guide gives a simple, step-by-step checklist to coordinate every account, pause automatic purchases, pick safe replacement securities, and what to tell your CPA so your harvested losses actually stick.
Understanding Wash Sale Rules Across Multiple Accounts
The wash sale rule blocks you from claiming a capital loss if you buy a substantially identical security within 30 days before or after you sell at a loss. That’s a 61-day window centered on your sale date. A lot of investors think it only applies inside one brokerage account. Wrong. Under Internal Revenue Code Section 1091, the IRS looks at every account you control as one big pool. Taxable accounts, Traditional IRAs, Roth IRAs, your employer’s 401(k), and even your spouse’s accounts if you file jointly.
Here’s where people get burned. You sell AAPL at a loss in your Fidelity taxable account on Monday, then buy it in your Schwab Roth IRA on Tuesday. Neither broker flags it on your Form 1099-B. Both custodians only report wash sales when the loss and the repurchase happen in the same account with the same CUSIP. Cross-account wash sales? Totally on you to find and report. The IRS still expects you to disallow the loss, fix your cost basis if you repurchased in a taxable account, and file Form 8949 with the right codes and amounts.
Buying inside any IRA or Roth IRA during that 61-day window creates a really painful outcome. Revenue Ruling 2008-5 is clear: sell at a loss in a taxable account and buy the same security in any IRA within 61 days, the loss disappears forever. You can’t add it to the IRA’s basis because IRAs don’t have cost basis. The tax benefit just vanishes. Same thing with employer 401(k) plans, even when contributions happen automatically through payroll. Sell XYZ at a loss on June 1, and your next paycheck buys XYZ in your 401(k) on June 10? Loss disallowed. Before you harvest anything, you need to know every account that might touch the same security over the next 61 days.
Coordinating Multiple Accounts to Avoid Wash Sale Conflicts
The simplest fix is a household trading calendar that tracks every buy and sell across every account you and your spouse control. List all taxable brokerage accounts, all IRAs and Roth IRAs, every employer retirement plan, and any joint or custodial accounts. Then set a 61-day blackout rule for each loss sale: no account buys the same ticker or a substantially identical security from 30 days before the sale through 30 days after. Mark the blackout window on a shared spreadsheet or inside your portfolio software so you catch conflicts before they happen.
Automatic investment plans cause the most coordination failures. Dividend reinvestment, systematic purchase plans, and payroll 401(k) contributions can all buy securities without you actively deciding anything. Before you sell at a loss, pause or turn off every automatic purchase that touches the same ticker in every account. Check transaction history for the prior 30 days to confirm none of those programs already bought the security. If they did, you already have a wash sale and need to adjust your reporting.
For couples filing jointly, build a single master file that pulls trade data from both spouses. Wash sale tests apply to purchases made by either spouse in any account either spouse controls. One spouse sells a position at a loss in Account A, the other buys the same security in Account B the next day? The IRS treats that as a wash sale even if the second spouse had no clue the first trade happened. Coordination isn’t optional. It’s baked into the tax code.
Timelines and Safe-Harbor Windows for Loss Harvesting
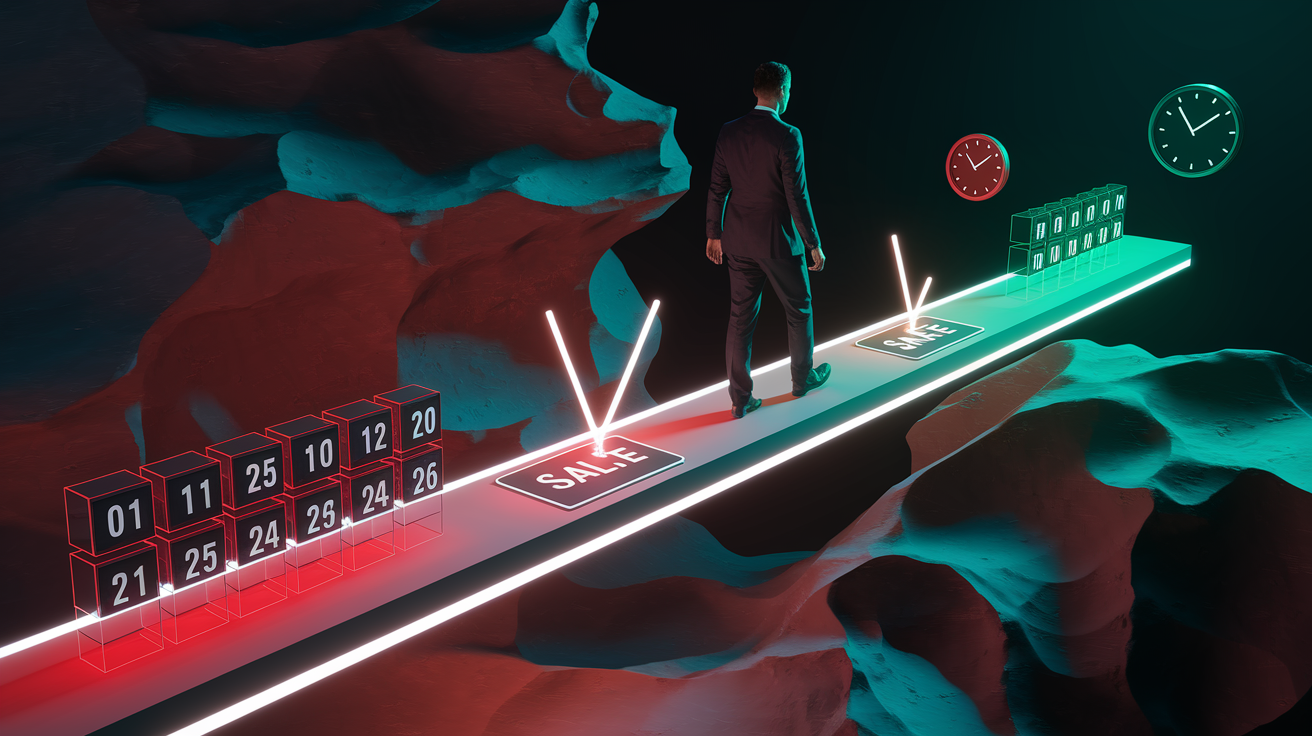
The safest timeline for a clean loss harvest looks like this: identify the loss position, confirm no purchases occurred in any controlled account during the prior 30 days, execute the sale, and wait 31 calendar days before buying the same security again. Day 31 after the sale is the first safe day to repurchase. If you need market exposure during that window, buy a replacement security that isn’t substantially identical.
The 61-day window breaks down like this:
-
Day -30 to Day -1 (before sale): Any purchase of the same or substantially identical security in any controlled account creates a forward wash sale that disallows the loss you’re about to take.
-
Day 0 (sale date): The trade date of your loss sale. The window centers here.
-
Day +1 to Day +30 (after sale): Any purchase of the same or substantially identical security in any controlled account triggers a standard wash sale.
-
Day +31 and beyond: You can repurchase the original security without triggering a wash sale tied to this specific loss sale.
A lot of advisors harvest losses near year end, then repurchase in early January to keep the loss inside the tax year while clearing the 30-day post-sale window. That only works if no other controlled account bought the security during December or the first week of January. Always count trade dates, not settlement dates. A purchase that settles in the new year but trades in December still lands inside the prior year’s wash sale window if it happens within 30 days after the loss sale.
Choosing Replacement Securities That Avoid “Substantially Identical” Classification
A replacement security lets you keep market exposure during the 61-day blackout without triggering a wash sale. The legal standard is “substantially identical,” a term the tax code doesn’t define with bright-line rules. The IRS looks at the economic substance of the two securities. If they deliver essentially the same investment result, they’re likely substantially identical even if they have different tickers or issuers.
The safest replacement strategy is to pick a security that tracks a different index or represents a different investment mandate. Sell an S&P 500 ETF at a loss and immediately buy a Russell 1000 ETF, and you get exposure to large-cap U.S. equities without recreating the same index position. The Russell 1000 holds roughly 1,000 stocks compared to the S&P 500’s 500 constituents, includes more mid-cap names, and uses a different weighting methodology. That difference in construction is usually enough to dodge “substantially identical” classification.
Swapping one S&P 500 ETF for another S&P 500 ETF from a different issuer is riskier. Even though VOO and SPY come from different fund companies, both track the same index with nearly identical holdings and weightings. The IRS hasn’t issued a ruling that definitively says two ETFs tracking the same index are substantially identical, but the economic outcome is so similar that many tax professionals treat it as a wash sale risk. A more conservative move is to replace an S&P 500 fund with a total-market fund like VTI, which includes small and mid-cap stocks and tracks a broader index. The added diversification and different index construction give you a stronger argument that the two funds aren’t substantially identical.
Avoiding IRA and Roth IRA Wash Sale Traps
The IRA wash sale trap is the most expensive mistake in cross-account loss harvesting. Sell a stock at a loss in your taxable brokerage account and buy the same stock inside any IRA or Roth IRA within the 61-day window, the loss gets disallowed under the wash sale rule and Revenue Ruling 2008-5 makes clear the disallowance is permanent. Normally, a disallowed wash sale adds the lost amount to the cost basis of the replacement shares, deferring the tax benefit until you sell the replacement. But IRAs and Roth IRAs don’t have cost basis. Contributions go in pre-tax or after-tax, and there’s no per-share basis to adjust. The disallowed loss just disappears.
Automatic contributions make this trap easy to fall into. Your paycheck funds a Traditional IRA every two weeks and the IRA buys a target-date fund that holds the same stock you just sold at a loss? You’ve triggered a permanent disallowance. The fix is to pause IRA contributions or redirect them to a different investment during any 61-day window that overlaps a taxable loss sale. Check your IRA’s transaction history for the 30 days before you plan to sell at a loss to confirm no recent purchases created a forward wash sale.
Roth conversions and recharacterizations don’t create new purchases for wash sale purposes, but buying securities inside the Roth after the conversion does. The same permanent-loss rule applies whether the IRA is Traditional, Roth, SEP, or SIMPLE. If you control the account and it’s classified as an IRA under the tax code, any purchase of a substantially identical security during the 61-day window will disallow the loss with no opportunity to recover the tax benefit later.
Spouse Account Rules and Community-Property Pitfalls
Purchases made by your spouse in any account your spouse controls can trigger a wash sale against losses you harvest in your own accounts. The tax code explicitly includes acquisitions by a spouse when figuring out whether a wash sale happened. This rule applies whether you file jointly or separately, though the reporting and tracking burden is simpler when filing jointly because all household activity lands on one return.
The most common spouse-account triggers:
Joint brokerage accounts: Either spouse can trade, and any purchase by either spouse during the 61-day window around the other spouse’s loss sale will disallow the loss.
Separate IRAs or Roth IRAs: One spouse sells AAPL at a loss in a taxable account and the other spouse buys AAPL in their own IRA the next week, the loss is disallowed and permanently lost.
Automatic investment plans in the spouse’s 401(k): Payroll contributions that purchase company stock or index funds matching the harvested security will create a wash sale even if the contributing spouse has no idea about the taxable loss sale.
A shared trading calendar solves most spouse-related wash sale conflicts. Before either spouse executes a loss sale, both review the calendar to confirm no purchases of the same security are scheduled in any household account during the 61-day window. Pause or redirect all automatic plans on both sides, and document the blackout period in writing. In community-property states, the attribution rules are even broader because each spouse gets treated as owning an interest in the other spouse’s separately titled accounts. The safest approach is to treat every account in the household as controlled by both spouses and coordinate all trading activity as a single pool.
Understanding “Substantially Identical” Securities
The term “substantially identical” shows up in Internal Revenue Code Section 1091 but isn’t defined by statute. The IRS and courts apply a facts-and-circumstances test focused on whether two securities deliver essentially the same economic result. The analysis looks at the structure of the investment, the underlying assets, the index or benchmark tracked, and the degree of overlap in holdings and weightings.
| Security Category | Key Considerations |
|---|---|
| Individual Stocks | Same company, same CUSIP = substantially identical. Different share classes (voting vs. non-voting) may still be substantially identical if economic rights are nearly the same. |
| Mutual Funds and ETFs | Same index, same issuer = high risk. Different index, different holdings count, or materially different weighting = safer. Tracking error, management strategy, and fund structure (open-end vs. ETF) all matter. |
| Bonds and Fixed Income | Same obligor, same maturity, same coupon = substantially identical. Different issuer or significantly different maturity may avoid the rule. |
For index funds and ETFs, the number of holdings and the index methodology matter a lot. An ETF holding roughly 4,100 stocks that tracks the total U.S. market isn’t substantially identical to an ETF holding around 2,500 stocks that tracks a broad U.S. index, even though both provide large-cap exposure. The difference in mid-cap and small-cap weighting, the inclusion of additional securities, and the distinct index construction create enough separation to support a non-identical classification.
Options, warrants, and convertible securities tied to the same underlying stock usually get treated as substantially identical to the stock itself. Sell stock at a loss and buy call options on the same stock within 30 days? You’ll trigger a wash sale. Same logic applies to preferred stock that converts into common stock on terms that make the two securities economically interchangeable.
Common Mistakes When Harvesting Across Accounts
The most frequent multi-account wash sale errors happen when investors forget about automatic systems running in the background. Dividend reinvestment programs, systematic investment plans, employer stock purchase plans, and 401(k) payroll deductions all create purchases without an active buy decision. Each of those programs can trigger a wash sale if they grab the same security you just sold at a loss.
Dividend reinvestment on: An investor sells VTI at a loss on May 15 to harvest $5,000. VTI pays a dividend on May 20, and the brokerage automatically reinvests it into more VTI shares. The loss gets disallowed because the reinvestment happened within 30 days after the sale.
Buying the same security in a different account the same day: Sell AAPL at a loss in Account A at 10:00 a.m. and buy AAPL in Account B at 2:00 p.m. to “stay invested”? Immediate wash sale. The timing within the same trading day doesn’t matter.
Forgetting prior purchases in an IRA: An investor contributes to a Roth IRA on April 1 and buys SPY. On April 20, the investor sells SPY at a loss in a taxable account, unaware that the April 1 Roth purchase sits inside the 30-day look-back window. The loss is permanently disallowed.
Spouse trading independently: One spouse sells QQQ at a loss to offset gains. The other spouse, managing a separate brokerage account, buys QQQ three days later as part of a rebalancing trade. The household wash sale disallows the loss.
Replacing with a “substantially identical” ETF: Sell VOO and immediately buy SPY to keep S&P 500 exposure. Both funds track the same index with nearly identical holdings, creating a high risk the IRS will treat them as substantially identical and disallow the loss.
Monitoring and Reporting Wash Sales Correctly
Brokers report wash sales on Form 1099-B only when both the loss sale and the repurchase happen within the same account and involve the same CUSIP. Cross-account wash sales don’t show up on any 1099-B. You’re responsible for finding them, calculating the disallowed loss, and reporting the adjustment on Form 8949. Use Code “W” in column (f) to flag a wash sale adjustment, enter the disallowed loss amount as a positive number in column (g), and column (h) will show the allowed loss after adjustment. In many cases, column (h) will be zero when the entire loss is disallowed.
The disallowed loss isn’t lost forever if you repurchased in a taxable account. Add the disallowed amount to the cost basis of the replacement shares. Sold 100 shares of XYZ for a $2,000 loss and bought 100 shares of XYZ in another taxable account for $10,000 within the wash sale window? Your new cost basis in the replacement shares is $12,000. The holding period of the original shares also “tacks” to the replacement shares, keeping any long-term holding period that had already started. Keep records of the original sale date, the replacement purchase date, the disallowed loss amount, and the adjusted basis calculation for at least three years after you file the return reporting the final sale of the replacement shares.
Final Words
You now know the key rules: the 30‑day before/after window, that purchases in IRAs and spouse accounts can bite you, and that “substantially identical” matters.
Coordinate trades across taxable, IRA, Roth, and spouse accounts. Use blackout dates or simple calendars. Pick replacement securities that aren’t substantially identical, and watch auto‑invest and dividend reinvestments.
For a quick next step, review how to avoid wash sale issues when harvesting losses across accounts and then check with your CPA. You’ll feel calmer and more in control next time.
FAQ
Q: Does the wash sale rule apply across multiple accounts?
A: The wash sale rule applies across multiple accounts. It disallows a loss if you buy a substantially identical security in any taxable account, IRA, 401(k), or a spouse’s account within the 30‑day window.
Q: Does the wash sale rule apply to losses? How to handle wash sale loss disallowed?
A: The wash sale rule applies to losses: it disallows a loss when you buy a substantially identical security within 30 days. If disallowed, add that loss to the replacement share’s cost basis; IRA repurchases can make the loss permanent.
Q: How do you eliminate the wash sale rule?
A: You eliminate the wash sale rule by avoiding repurchases of substantially identical securities within the 30‑day before-and-after window. Instead wait 31 days or buy a clearly different replacement ETF or fund, and coordinate across household accounts.

