
What if a falling crypto price could actually cut your tax bill?
Tax-loss harvesting means selling crypto at a loss so that loss offsets gains and can lower your taxable income now or later.
Right now crypto avoids the wash-sale rule that limits this tactic for stocks, so you can often sell and buy back without losing the tax benefit.
This post gives clear, step-by-step strategies for taxable accounts — when to harvest, which cost-basis method to use, how to repurchase, and the key questions to ask your CPA.
Defining Tax-Loss Harvesting Strategies for Crypto in Taxable Accounts
Tax-loss harvesting means selling cryptocurrency at a loss so you can actually use that loss to cut your taxable income. In taxable accounts, realized losses first wipe out capital gains you made during the same year. Then you can deduct up to $3,000 of leftover losses against your regular income each year, and anything beyond that rolls forward indefinitely. The IRS classified crypto as property back in 2014, so every time you sell or trade, you’re triggering a capital gain or loss based on what you got minus what you paid.
What makes crypto different from stocks is that the wash-sale rule doesn’t apply. Yet. With traditional securities, if you sell at a loss and buy back the same thing within 30 days, the IRS disallows your deduction. Crypto gets treated as property instead of a security, so right now you can sell Bitcoin at a loss on Monday, buy it back Tuesday, and still claim the tax benefit. This makes crypto loss harvesting way more flexible than doing it with stocks, though Congress keeps trying to close that loophole.
Harvesting losses in your taxable crypto holdings gets you a few things:
- Cuts your tax bill for the current year by offsetting gains you realized
- Builds loss carryforwards that can shield future gains
- Lets you deduct up to $3,000 against ordinary income, which might be taxed as high as 37%
- Keeps you in the market when you repurchase right away
- Gives you a chance to rebalance while grabbing a tax break
How Crypto Tax-Loss Harvesting Works Mechanically
When you sell crypto for less than you paid, you realize a capital loss. The loss equals the difference between your sale price and your original cost basis. Say you buy 0.25 BTC for $3,000 in June. Nothing happens tax-wise until you sell. You sell that 0.25 BTC for $2,000 in October, your realized loss is $1,000. Sale price of $2,000 minus cost basis of $3,000 equals negative $1,000. That $1,000 is now available to offset gains from other sales, and if there aren’t any gains, you can apply up to $3,000 against your paycheck income and carry the rest forward.
This also works for crypto-to-crypto trades. Swapping Ethereum for Solana counts as selling your Ethereum, even though you never touched dollars. If your Ethereum dropped in value since you bought it, that swap realizes a loss. After you sell or swap to lock in the loss, you can immediately buy back the same crypto without the wash-sale rule kicking in, which means you keep your portfolio allocation and still get the tax deduction. The table below breaks down how different moves affect your taxes:
| Event | Tax Effect |
|---|---|
| Holding crypto as price falls | No tax effect (unrealized loss) |
| Selling crypto below cost basis | Realized capital loss; offsets gains or ordinary income |
| Swapping crypto-to-crypto below original cost | Realized capital loss on the disposed asset |
| Repurchasing same crypto immediately | New cost basis set at repurchase price; loss remains valid under current rules |
Core Crypto Tax-Loss Harvesting Strategies for Taxable Accounts
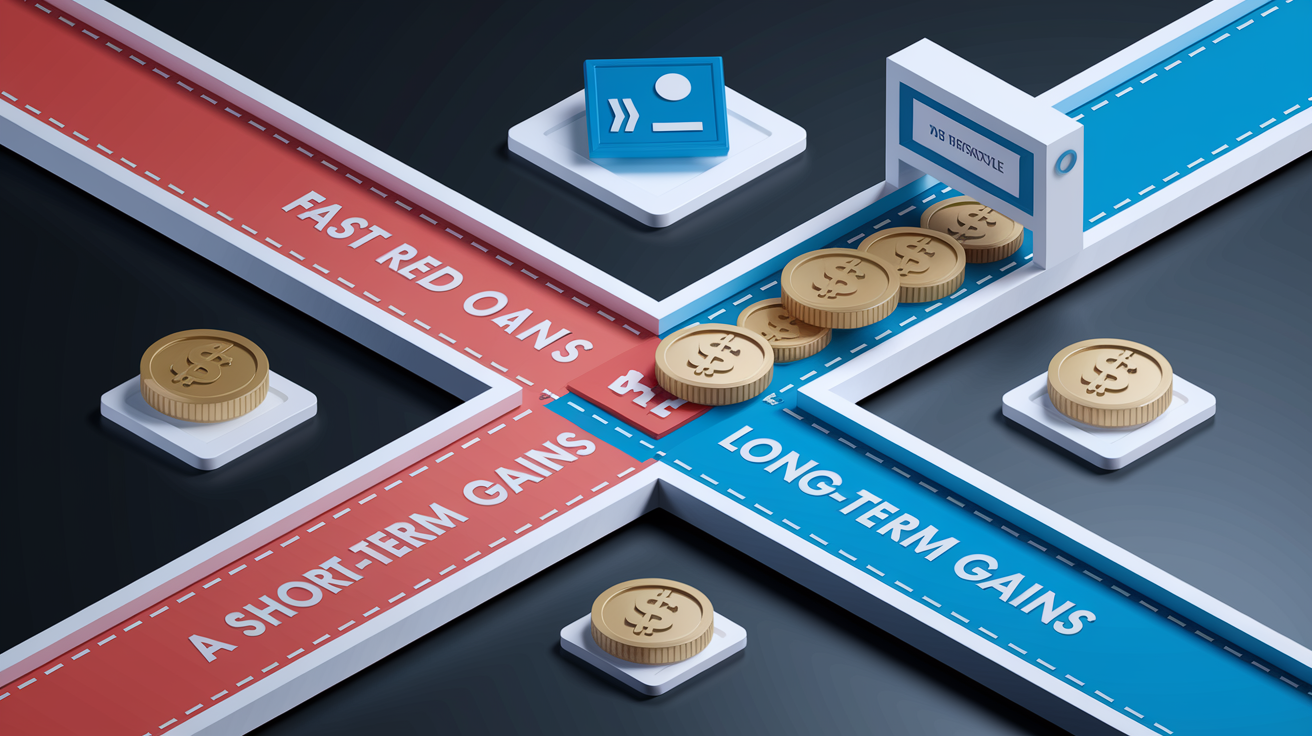
Short-term capital gains from crypto you held one year or less get taxed as ordinary income, up to 37%. Long-term gains from stuff you held over a year face capital gains rates of 0%, 15%, or 20%, depending on your income. Because short-term rates can be almost double, matching short-term losses with short-term gains gives you the biggest tax savings per dollar of loss. Losses first cancel out gains of the same type. Short-term losses hit short-term gains, long-term losses hit long-term gains. Then any leftover losses cross over to the other type.
Here’s a concrete example. You sold Bitcoin in March and realized a $10,000 short-term gain. In November, Ethereum is down, and selling it would produce a $5,000 short-term loss. If you harvest that Ethereum loss before year-end, your net short-term gain drops to $5,000 instead of $10,000, saving you tax on that $5,000 offset. If you’re in the 24% bracket, that $5,000 offset saves you $1,200 in federal tax. If the Ethereum loss had been long-term, it would still offset the short-term gain after netting, but the order affects which rate applies.
Even when you don’t have any gains, harvesting losses builds a reserve. Capital losses carry forward indefinitely, and up to $3,000 per year can offset ordinary income. If you’re in the 32% bracket, a $3,000 ordinary income deduction saves you $960 every year. Strategies to guide your decisions:
- Focus on harvesting short-term losses when you have short-term gains, targeting the highest tax bracket
- Harvest losses late in the year after reviewing what you’ve realized, so you can pair them efficiently
- Keep your portfolio allocation by repurchasing the same asset right away or swapping into something similar
- In high income years, accelerate loss realization to offset gains at your peak rate
- In low income years, think about deferring harvesting if you expect bigger gains or income next year
- Build multi-year loss carryforwards as a cushion against future sales or bull market runs
Cost Basis Methods for Optimizing Crypto Loss Harvesting
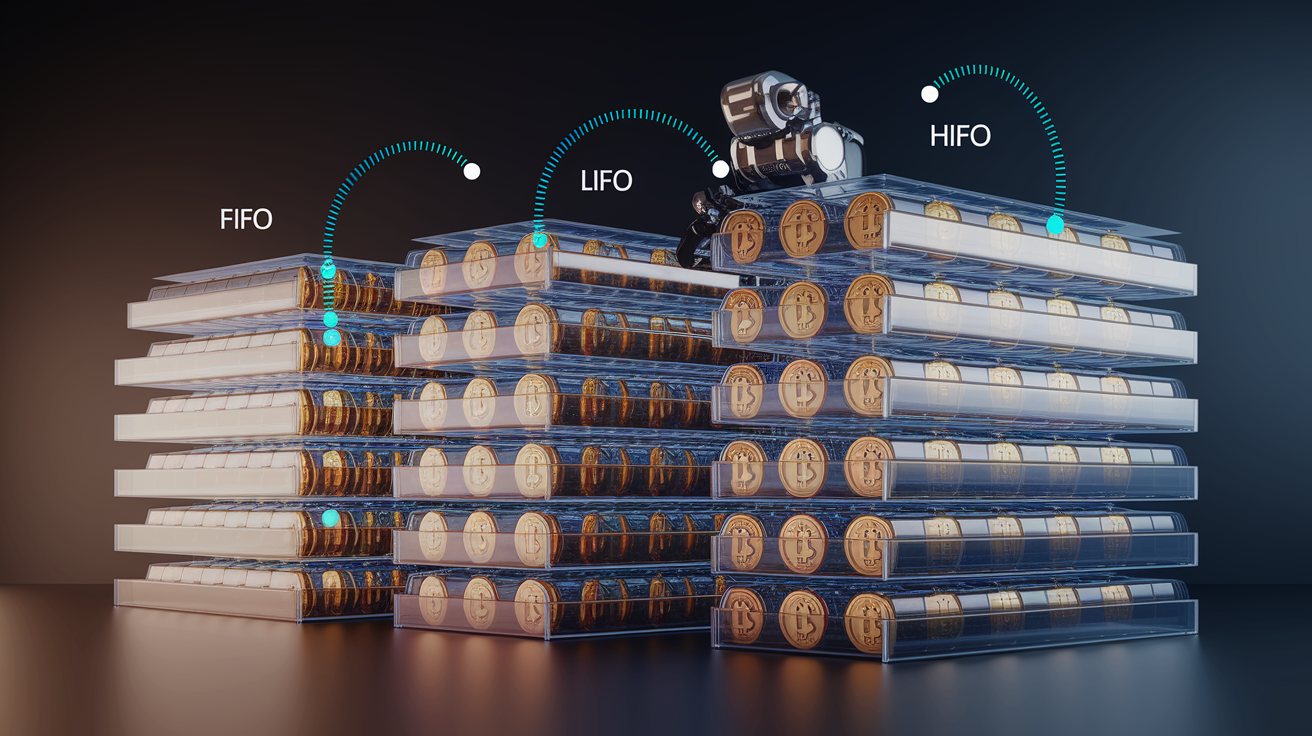
The cost basis method you pick determines which lots you’re selling and how big your realized loss will be. Starting January 1, 2026, centralized exchanges will report cost basis to the IRS and default to FIFO (first in, first out) if you don’t specify. Choosing deliberately can mean the difference between a big deductible loss and an unexpected gain.
Specific Identification
Specific identification lets you hand-pick which lot to sell. Full control. If you bought Bitcoin at $60,000 in April and at $30,000 in September, and the price is now $35,000, selling the $60,000 lot produces a $25,000 loss while selling the $30,000 lot would generate a $5,000 gain. Spec ID is the most flexible method for tax-loss harvesting because it lets you target your highest cost lots. Most platforms require you to designate the specific lot before or when you sell, and you need to keep records proving which lot you chose.
FIFO
First in, first out sells your oldest crypto first. FIFO is simple and conservative, but in a rising market your oldest lots often have the lowest cost basis, which means gains instead of losses. Say you bought Bitcoin at $10,000 three years ago and again at $50,000 six months ago. Price is now $35,000. FIFO forces you to sell the $10,000 lot, realizing a $25,000 gain rather than harvesting a $15,000 loss from the newer lot. FIFO becomes the default on exchanges after 2025 unless you elect otherwise.
LIFO
Last in, first out sells your newest purchases first. LIFO can work well during bear markets when recent buys have higher cost bases. If you bought Bitcoin at $45,000, $40,000, and $30,000, and the price is now $25,000, LIFO automatically sells the $45,000 lot, producing a $20,000 loss. LIFO requires consistent application once you elect it and isn’t common on retail platforms.
HIFO
Highest in, first out always sells the lot with the highest cost basis first, maximizing your realized loss every time. Using the earlier example, HIFO would sell the $50,000 lot when the price is $35,000, locking in a $15,000 loss. HIFO is best for pure tax-loss harvesting but requires detailed lot tracking and may not be supported everywhere. Works best when combined with Spec ID and manual recordkeeping.
| Method | Best Use Case | Risk |
|---|---|---|
| Specific Identification | Maximum control; ideal for harvesting specific high cost lots | Requires detailed records and platform support |
| FIFO | Simple administration; good for consistent gain realization | Often produces gains in rising markets instead of losses |
| LIFO | Bear markets where recent purchases are underwater | Must apply consistently; limited platform support |
| HIFO | Aggressive loss harvesting; sells highest cost basis first | Complex tracking; not universally available on exchanges |
Real-World Crypto Tax-Loss Harvesting Examples with Numeric Calculations
First example: you purchased 1 BTC at $40,000 in February. By October, Bitcoin has fallen to $30,000. Selling that 1 BTC for $30,000 realizes a $10,000 capital loss. Sale price of $30,000 minus cost basis of $40,000 equals negative $10,000. If you realized $15,000 in capital gains earlier in the year from selling Ethereum, the $10,000 Bitcoin loss brings your net taxable gain down to $5,000. At a 15% long-term capital gains rate, you save $1,500 in tax. That’s $10,000 loss times 15%. You can immediately repurchase the Bitcoin at $30,000, resetting your cost basis to $30,000 and keeping your exposure if the price recovers.
Second example: you hold multiple positions and have realized $50,000 in short-term capital gains. You also hold Bitcoin with an $18,000 unrealized loss. Original cost basis of $53,000, current value $35,000. Selling the Bitcoin to harvest the $18,000 loss brings your net taxable gain down to $32,000. That’s $50,000 gains minus $18,000 losses equals $32,000 net. If you’re in the 24% marginal tax bracket, the $18,000 offset saves $4,320 in federal tax. That’s $18,000 times 24%. After the sale, you can reinvest the $35,000 proceeds into Bitcoin or a different crypto, preserving your market allocation while capturing the immediate tax benefit. The table below summarizes both scenarios:
| Asset | Cost Basis | Sale Price | Resulting Loss | Tax Impact |
|---|---|---|---|---|
| 1 BTC (Example 1) | $40,000 | $30,000 | $10,000 | $1,500 saved at 15% rate |
| Bitcoin (Example 2) | $53,000 | $35,000 | $18,000 | $4,320 saved at 24% rate |
| Ethereum (offset scenario) | $40,000 | $35,000 | $5,000 | Reduces $10,000 BTC gain to $5,000 net |
| Solana (per token) | $100 | $50 | $50 per token | Loss scales with quantity sold |
| Carryforward (no gains year) | varies | varies | $10,000 | $3,000 offsets ordinary income; $7,000 carries forward |
Navigating Crypto Wash-Sale Rules, Rebalancing, and Replacement Asset Choices
Under current IRS guidance, the 30 day wash-sale rule applies to stocks and securities but not to directly held cryptocurrency. So you can sell Bitcoin at a loss on Monday, realize the tax deduction, and repurchase the same Bitcoin on Tuesday without the IRS disallowing your loss. That’s a temporary advantage, not a permanent one. Proposed legislation has repeatedly tried to extend wash-sale rules to digital assets, and a lot of tax professionals expect the rule to eventually cover crypto.
Crypto ETFs and exchange-traded products are securities, so the wash-sale rule does apply. If you sell a Bitcoin ETF at a loss and repurchase the same or substantially identical ETF within 30 days before or after the sale, the loss is disallowed and gets added to the cost basis of the replacement shares. To avoid triggering a wash sale when working with crypto ETFs, wait 31 days before repurchasing, or substitute with direct Bitcoin holdings or a different but related ETF.
When you sell crypto to harvest a loss and want to stay in the market, you’ve got a few replacement tactics:
- Immediately repurchase the identical cryptocurrency (currently allowed for direct holdings)
- Swap into a different but correlated cryptocurrency to keep general market exposure while technically changing your position
- Move proceeds into stablecoins temporarily, then repurchase after checking market conditions
- Use a basket or index approach, buying multiple altcoins to maintain diversified crypto exposure without jumping back into the exact same position
Each approach resets your cost basis to the market value at the time you repurchase. If you sell Bitcoin at $30,000 and immediately rebuy at the same price, your new cost basis is $30,000, lower than your original $40,000 basis. This reset can mean bigger taxable gains when you eventually sell at a profit, so weigh the immediate tax benefit against the future tax cost.
Costs, Risks, and Pitfalls of Crypto Tax-Loss Harvesting
Transaction costs can quickly eat up or eliminate the tax benefit of harvesting a loss. Centralized exchanges charge trading fees anywhere from 0.1% to 4%, depending on your volume tier and payment method. Add in bid-ask spreads, especially during volatile periods or for less liquid tokens, and the round-trip cost of selling and repurchasing can exceed the tax savings on small positions. Network fees for moving crypto between wallets or exchanges add another expense. Before you execute a harvest, calculate your expected tax benefit (realized loss times your marginal tax rate) and subtract all transaction costs to confirm you’re actually coming out ahead.
Resetting your cost basis downward is a hidden risk. When you sell at $30,000 and repurchase at $30,000, your new basis is $30,000 instead of the original $40,000. If Bitcoin later climbs to $50,000 and you sell, your taxable gain is $20,000 instead of the $10,000 it would’ve been had you never harvested the loss. The benefit of today’s deduction can be offset or reversed by a higher future tax bill, especially if your tax bracket goes up or long-term rates rise. Some people call this “selling your tax deferral.”
Common pitfalls:
- Harvesting losses in low tax years and recognizing gains in high tax years, which reverses the benefit
- Ignoring trading fees and network costs, resulting in a net loss after tax savings
- Failing to track new cost basis after repurchase, which leads to wrong gain calculations later
- Over-harvesting and creating unnecessary turnover that increases total transaction costs and complexity
- Repurchasing a crypto ETF within 30 days instead of direct holdings, triggering a disallowed wash sale
Record-Keeping, Reporting, and Documentation for Crypto Loss Harvesting
The IRS requires comprehensive documentation of every crypto transaction. For each sale that realizes a loss, you need to record the date and time you bought, the date and time you sold, the quantity sold, the cost basis (including any fees paid when you bought), the gross proceeds, any fees paid when you sold, and the exchange or wallet you used. These details go on IRS Form 8949, where each transaction is listed individually, and Schedule D, where net capital gains and losses get calculated and carried forward.
Tracking unrealized versus realized losses matters. An unrealized loss exists when you hold crypto below your cost basis but haven’t sold it yet. It provides no current tax benefit. A realized loss happens the moment you execute a sale or exchange, triggering the deduction. Keeping a running ledger that separates these categories helps you plan harvesting opportunities throughout the year and reconcile your records with exchange statements and IRS forms during tax filing.
Good recordkeeping protects you in an audit. If the IRS questions a claimed loss, you have to prove the acquisition date and cost basis of the lot you sold, the sale date and proceeds, and that you correctly identified the lot under your chosen accounting method. Keep trade confirmations, blockchain transaction hashes, wallet addresses, and notes showing which lot you designated when using Spec ID. A lot of investors consolidate records in a spreadsheet or dedicated crypto tax software that auto-generates Form 8949.
Required record fields for every transaction:
- Date and time of acquisition
- Date and time of disposal
- Asset name and quantity
- Cost basis per unit and total
- Sale proceeds per unit and total
- Exchange, wallet, or platform used
| Field | Description |
|---|---|
| Acquisition Date | Date and time you purchased or received the crypto |
| Disposal Date | Date and time you sold, traded, or otherwise disposed of the crypto |
| Cost Basis | Total amount paid (including fees) to acquire the specific lot sold |
| Proceeds | Total amount received (after fees) from the sale or exchange |
| Source | Exchange, wallet address, or platform where the transaction occurred |
Timing Strategies: When to Harvest Crypto Losses in Taxable Accounts
The final deadline to realize losses for the current tax year is December 31. Any sale you execute on or before that date counts toward the year’s capital gains and losses. Sales on January 1 or later apply to the following year. A lot of investors wait until late December to review their positions, but that reactive approach often misses better opportunities earlier in the year when prices dip and recover quickly.
Harvesting during the year captures losses during temporary pullbacks. If Bitcoin drops 20% in May, selling to realize the loss and immediately repurchasing locks in the deduction while keeping your exposure to a summer rally. Waiting until December to check your portfolio means you might miss that May dip entirely if prices have recovered by then. Frequent monitoring and opportunistic execution typically generate bigger cumulative losses than a single year-end sweep.
Even when you don’t have capital gains in the current year, harvesting losses makes sense. Realized losses carry forward indefinitely, building a reserve that shelters gains in future years. You can also deduct up to $3,000 of capital losses against ordinary income each year. In high income years, that $3,000 deduction at a 35% marginal rate saves $1,050, and the remainder carries forward to offset next year’s gains or another $3,000 of ordinary income.
Timing signals that suggest harvesting now:
- You’ve realized significant gains earlier in the year and need offsets before December 31
- A holding has dropped substantially and you think recovery is unlikely soon
- You’re rebalancing your portfolio and can harvest losses while adjusting allocation
- Proposed wash-sale legislation is advancing, and you want to take advantage of the current no waiting period rule before it changes
Applying These Crypto Harvesting Strategies in Your Own Taxable Account
Putting tax-loss harvesting into practice in your taxable account starts with a clear picture of your current positions. Pull your transaction history from every exchange and wallet you’ve used, then identify which lots are underwater. Current market value below your cost basis. Calculate the unrealized loss for each lot (current value minus cost basis) and rank them by size. If you use Spec ID, you’ve got full control to pick the highest cost lots. If your platform defaults to FIFO, check whether you can override that method before you execute the sale.
Next, estimate the tax benefit and weigh it against transaction costs. Multiply your planned realized loss by your marginal tax rate (short-term or long-term, depending on holding period) to calculate the dollar value of the tax savings. Then subtract trading fees, bid-ask spread costs, and any network or custody fees. If the net benefit is positive and meaningful, go ahead with the sale. Right after selling, decide whether to repurchase the same asset to maintain exposure, swap into a different cryptocurrency, or hold the proceeds in cash or stablecoins. Update your records with the new cost basis and holding period start date for any repurchased lots, and file the realized loss on Form 8949 when you prepare your tax return.
Practical six step process:
- Inventory all taxable account crypto positions by date, quantity, and cost basis
- Identify underwater lots and calculate the unrealized loss per lot
- Estimate your tax benefit (realized loss times marginal tax rate) and subtract all transaction costs to confirm net savings
- Execute the sale to realize the loss, noting date, time, proceeds, and fees
- Optionally repurchase the same or substitute crypto to maintain allocation, recording the new cost basis and acquisition date
- Report realized losses on Form 8949, net them against gains, apply the $3,000 ordinary income deduction if applicable, and carry forward any unused losses to future years
Final Words
You’re selling a losing token to lock a loss and lower tax on a bigger gain. That’s tax-loss harvesting in action.
This guide covered what harvesting is, step-by-step mechanics, cost-basis choices, timing and replacement-asset tactics, common risks, and the record-keeping you’ll need.
Use these crypto tax-loss harvesting strategies for taxable accounts to trim taxes, keep market exposure, and build a repeatable year-round plan. If you’re unsure, take your notes to a CPA — planning before you sell pays off.
FAQ
Q: What is crypto tax-loss harvesting?
A: Crypto tax-loss harvesting is selling crypto in a taxable account at a loss to create realized losses that offset capital gains, reduce taxable income (up to $3,000 per year), and carry forward unused losses.
Q: Why does tax-loss harvesting apply to crypto in taxable accounts?
A: Tax-loss harvesting applies to crypto in taxable accounts because the IRS treats crypto as property and every sale or trade creates a taxable gain or loss you can use to offset other gains.
Q: How do realized crypto losses reduce my taxable gains?
A: Realized crypto losses reduce taxable gains by offsetting gains first (short- and long-term by type), then up to $3,000 can lower ordinary income, with any leftover losses carried forward indefinitely.
Q: How does crypto tax-loss harvesting work step-by-step?
A: Crypto tax-loss harvesting works by identifying underwater lots, selling to realize the loss, optionally repurchasing to maintain exposure, updating cost basis, and reporting the loss on Form 8949/Schedule D.
Q: Can I immediately repurchase crypto after harvesting losses?
A: You can generally immediately repurchase crypto after harvesting losses because the wash-sale rule doesn’t currently apply to crypto, though that could change and ETFs tied to crypto are subject to wash-sale rules.
Q: Are crypto-to-crypto trades taxable events?
A: Crypto-to-crypto trades are taxable events because they’re treated as disposals of property; you realize a gain or loss based on proceeds versus cost basis whenever you trade one crypto for another.
Q: Which cost-basis method helps maximize harvesting benefits?
A: Specific identification or HIFO (highest in, first out) usually maximizes recognized losses by letting you pick high-cost lots; FIFO can create unintended gains and may be broker-default in some future rules.
Q: What are the main costs and risks of harvesting crypto losses?
A: Main costs and risks include trading fees that can exceed tax benefits, resetting to a lower cost basis (bigger future gains), tax-bracket timing, and possible future wash-sale rules or regulation changes.
Q: When is the best time to harvest crypto losses?
A: The best time to harvest crypto losses is before year-end for that tax year, during meaningful intra-year dips, or when you expect lower future tax rates—sell by December 31 to realize the loss that year.
Q: What records do I need to document crypto loss harvesting?
A: You need acquisition and sale dates, cost basis, proceeds, transaction fees, exchange source, and lot ID; report sales on Form 8949 and Schedule D and keep backup records for audits.
Q: How should I pair losses with gains strategically?
A: Pair losses with short-term gains first (they’re taxed as ordinary income), use losses to net against long-term gains, build carryforwards for future years, and rebalance while maintaining desired exposure.
Q: How do I implement a simple harvesting plan in my taxable account?
A: To implement harvesting: 1) list underwater lots, 2) estimate tax benefit vs fees, 3) sell chosen lots, 4) decide on repurchase or replacement asset, 5) update records, 6) report on tax forms.

