
Think the sale price is what you’ll walk away with?
Before you list a house, sell stock, or offload rental property, the actual cash can shrink by tens of thousands.
This post shows simple formulas and four clear steps to estimate your capital gains tax and net proceeds before you hit sell.
You’ll learn the five numbers to gather, the common mistakes that inflate tax bills, and a quick example you can run in minutes.
Defining Capital Gains, Net Proceeds, and the Exact Steps to Estimate Taxes Before Selling
Before you list a house, sell stock, or offload rental property, you need a clear picture of the actual cash you’ll walk away with. A sale price of $500,000 sounds great until you subtract agent commissions, closing costs, mortgage payoff, federal capital gains tax, state tax, and other fees. What feels like a big number on paper can shrink fast. The difference between gross sale price and net proceeds is often tens of thousands of dollars, and miscalculating it can derail your next financial move.
The core formulas are simple. Capital gain = Sale price − Adjusted cost basis − Selling costs. Your adjusted cost basis starts with what you paid, then adds capital improvements (like a new roof or kitchen remodel), and subtracts accumulated depreciation if the asset was rented or used in business. Once you know your gain, you calculate tax: Tax owed = Taxable gain × Applicable tax rate. Finally, Net proceeds = Sale price − Selling costs − Federal tax − State tax − Other fees. These three formulas stack together to show exactly what lands in your bank account.
To run the calculation, you need five critical inputs:
- Sale price: the agreed contract amount or final transaction value.
- Adjusted cost basis: purchase price plus improvements minus depreciation.
- Selling costs: agent commissions (often 5–6% for real estate), closing costs, transfer taxes, staging, legal fees, and broker fees.
- Tax rates: federal short-term (10–37%) or long-term (0%, 15%, 20%), plus Net Investment Income Tax (3.8% for high earners), plus state rate (0–13.3% depending on location).
- Other mandatory fees: depreciation recapture tax (up to 25% on rental property), loan payoff, seller credits, or escrow adjustments.
Here’s a quick example. You bought a home for $300,000, added a $75,000 room addition, and sold it for $600,000. Your adjusted basis is $375,000, so your gain is $225,000. If you’re single and meet the primary residence tests, you exclude $250,000 of gain, leaving $0 taxable. After a $36,000 commission (6%) and $5,000 in closing costs, your net proceeds are approximately $600,000 − $36,000 − $5,000 = $559,000. If the exclusion didn’t apply and you paid 15% federal long-term tax on $225,000, you’d owe $33,750, dropping net proceeds to around $525,250 before state tax.
Why Estimating Capital Gains Tax and Net Proceeds Is Complicated
Sellers regularly underestimate their tax bill or overestimate their cash at closing for four reasons. First, basis adjustments aren’t obvious. You must track every capital improvement, separate them from routine repairs, and subtract accumulated depreciation if the asset was rented or used in business. Miss a $20,000 kitchen remodel receipt and you’ll pay tax on an extra $20,000 of phantom gain.
Second, holding period determines whether you face short-term ordinary income rates (up to 37%) or long-term preferential rates (0%, 15%, 20%). Selling one day too early can double your tax rate.
Third, selling expenses reduce both your taxable gain and your net cash, but tracking them requires detail. Real estate commissions of 5–6%, $2,000–$10,000 in closing costs, transfer taxes, staging fees, and legal bills all count. Stock sales may carry only a $10 broker fee, but mutual funds can have redemption loads.
Fourth, state and local taxes stack on top of federal. California adds up to 13.3%, New York up to 10%, while Florida and Texas add zero. Depreciation recapture on rental property triggers an additional federal tax of up to 25% on the depreciated amount before you even get to capital gains rates. The Net Investment Income Tax adds 3.8% when your modified adjusted gross income exceeds $200,000 single or $250,000 married filing jointly.
| Factor | Why It Complicates Taxes | Typical Impact |
|---|---|---|
| Basis adjustments | Improvements increase basis and reduce gain; depreciation lowers basis and increases gain | $10,000–$100,000+ swing in taxable gain |
| Depreciation recapture | Rental or business use triggers recapture taxed at up to 25% on depreciation taken | $5,000–$20,000+ additional tax on a typical rental property |
| Tax-rate variability | Short-term (10–37%) vs long-term (0/15/20%) plus NIIT (3.8%) plus state (0–13.3%) | Combined effective rate can range from 0% to 54%+ |
| Selling expenses | Reduce both taxable gain and net proceeds; must be documented to deduct | $10,000–$50,000 for real estate; $10–$1,000 for securities |
Step-by-Step Capital Gain Calculation Before Selling an Asset
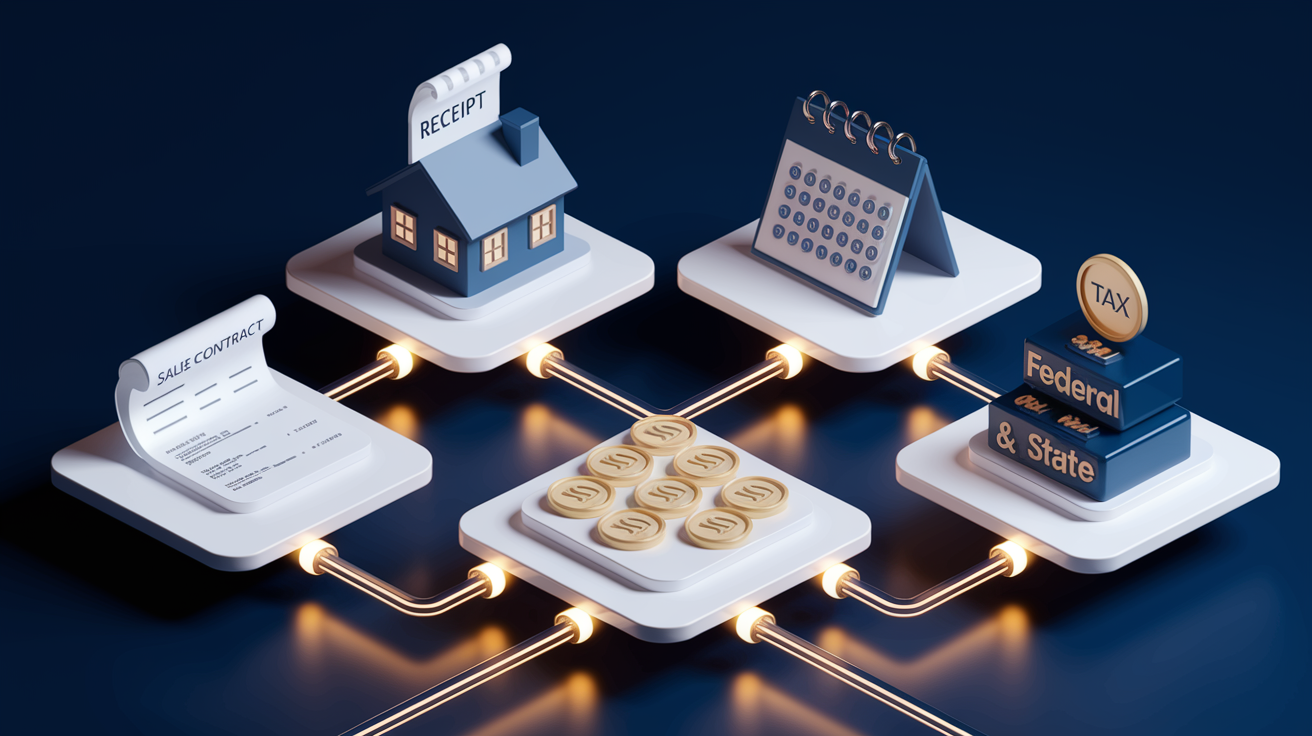
Run through these four steps in order, using real numbers from your purchase records and current sale contract.
Step 1: Determine Cost Basis
Start with what you originally paid for the asset. Add capital improvements, which are permanent upgrades that increase value or extend useful life. Think new HVAC system, roof, kitchen remodel, room addition, or paving a driveway. Don’t add routine repairs like painting, fixing a leak, or replacing a broken window.
If you owned rental property or used the asset in business, subtract accumulated depreciation (the total depreciation deductions you claimed on tax returns). For securities, add reinvested dividends and adjust for stock splits.
Your adjusted cost basis formula is: Purchase price + Capital improvements + Acquisition costs (legal, recording fees) − Accumulated depreciation − Previous casualty loss deductions.
Example: bought a rental for $250,000, added $20,000 improvements, took $40,000 depreciation over ten years. Adjusted basis = $250,000 + $20,000 − $40,000 = $230,000.
Step 2: Determine Selling Price Minus Commissions and Fees
Take the gross sale price from your contract. Subtract direct selling costs: real estate agent commissions (commonly 5–6% of sale price), advertising and staging expenses, legal fees, title insurance premiums paid by seller, transfer taxes, recording fees, escrow fees, and any seller credits or concessions. For securities, subtract broker commissions or transaction fees. For business assets, include auctioneer fees or listing costs.
This gives you net sale proceeds before tax. Example: $500,000 sale price − $30,000 commission (6%) − $5,000 closing costs = $465,000.
Step 3: Identify Holding Period and Apply Correct Tax Rate
Count from the day after you acquired the asset to the day you sold it. Short-term means you held the asset one year or less; gains are taxed as ordinary income at your marginal federal rate (10%, 12%, 22%, 24%, 32%, 35%, or 37% depending on taxable income).
Long-term means you held the asset more than one year; gains are taxed at preferential federal rates of 0%, 15%, or 20% based on your taxable income brackets. Typical 2025 thresholds for long-term rates: 0% up to roughly $48,350 single / $96,700 married filing jointly; 15% up to $533,400 single / $600,050 married filing jointly; 20% above those amounts.
Add the Net Investment Income Tax of 3.8% if your modified adjusted gross income exceeds $200,000 single / $250,000 married filing jointly.
Example: $100,000 long-term gain, 15% federal rate, 3.8% NIIT. Combined federal = 18.8% = $18,800.
Step 4: Apply Federal, NIIT, and State Taxes
Multiply your taxable gain by the federal rate from Step 3. If you qualify for the primary residence exclusion ($250,000 single / $500,000 married filing jointly), subtract that exclusion from your gain first. Add NIIT if applicable. Then multiply your taxable gain by your state’s capital gains rate (California up to 13.3%, New York roughly 10%, Florida and Texas 0%).
Depreciation recapture on rental property is taxed separately at up to 25% on the depreciation amount before applying the long-term rate to the remaining gain. Sum all tax components to get total tax owed.
Example: $70,000 rental property gain with $20,000 depreciation recapture. Recapture tax = $20,000 × 25% = $5,000; remaining $50,000 × 15% = $7,500; total federal = $12,500 plus state.
Five common calculation mistakes to avoid:
- Using purchase price as basis without adding improvements or subtracting depreciation.
- Forgetting to subtract selling costs from both taxable gain and net proceeds.
- Counting short-term holding when you held the asset exactly one year (you need one year and one day).
- Applying long-term rates to depreciation recapture (it’s taxed at up to 25%).
- Ignoring state tax or NIIT when your income crosses the threshold.
Calculating Net Proceeds: Converting Gross Sale Price into Real Cash
Net proceeds is the number that actually hits your account after every deduction is subtracted from the sale price. Start with the contract price, then pull out every cost: selling expenses, taxes, loan payoffs, and other mandatory fees.
The formula is Net proceeds = Sale price − Selling costs − Federal capital gains tax − State capital gains tax − NIIT − Depreciation recapture tax − Other transaction fees − Outstanding mortgage balance − Seller credits. This is the figure that tells you whether you can afford your next down payment, pay off debts, or fund a new investment.
Selling costs come in layers. Real estate transactions typically carry agent commissions of 5–6%, closing costs of $2,000–$10,000 (title insurance, escrow, attorney fees, recording fees, transfer taxes), and optional expenses like staging ($1,000–$5,000) or repair credits negotiated in the contract. Stock and mutual fund sales usually carry minimal broker fees ($0–$10 per trade at most brokerages), but some funds charge redemption fees or back-end loads. Business asset sales may include auctioneer commissions, broker fees, or legal costs.
Document every expense with receipts and closing statements, because these reduce both your taxable gain and your cash.
| Deduction Type | Typical Range | Applies To |
|---|---|---|
| Agent commissions | 5–6% of sale price | Real estate, some business assets |
| Closing costs | $2,000–$10,000 | Real estate (title, escrow, recording, transfer taxes) |
| Transfer taxes | 0.1–2% of sale price | Real estate (varies by state and locality) |
| Brokerage fees | $0–$10 per trade | Securities, mutual funds (redemption fees may apply) |
| Depreciation recapture / other taxes | Up to 25% on recaptured depreciation, plus NIIT 3.8% | Rental property, business assets |
Four common net-proceeds miscalculations sellers make:
- Forgetting to subtract the outstanding mortgage balance or home equity line payoff.
- Estimating taxes using only federal rates and ignoring state tax and NIIT.
- Not accounting for seller credits or repair allowances negotiated in the contract.
- Using gross sale price instead of net sale proceeds when planning the next purchase.
Worked Examples: Real Estate, Stocks, and Rental Property
Example 1: Home Sale Using Adjusted Basis and Primary Residence Exclusion
You bought your primary residence in 2022 for $450,000, spent $75,000 on a permitted room addition in 2023, and sold the home in 2025 for $600,000. Your adjusted cost basis is $450,000 + $75,000 = $525,000, so your raw capital gain is $600,000 − $525,000 = $75,000.
You meet the ownership and use tests (lived in the home as your main home for at least 2 of the last 5 years, owned it for at least 2 of the last 5 years, and haven’t used the exclusion in the prior 2 years), so you’re single and qualify for the $250,000 exclusion. Your taxable gain is $75,000 − $250,000 = $0. After a 6% agent commission ($36,000) and $5,000 in closing costs, your net proceeds before mortgage payoff are $600,000 − $36,000 − $5,000 − $0 tax = $559,000.
- Sale price: $600,000
- Adjusted basis: $525,000 (purchase $450,000 + improvements $75,000)
- Raw gain: $75,000
- Taxable gain after exclusion: $0
- Net proceeds: $559,000 (before mortgage payoff)
Example 2: Stock Sale (Long-Term vs Short-Term)
You bought 1,000 shares of a stock for $50,000 in January 2023 and sold them in March 2025 for $80,000. You held the shares for more than one year, so this is a long-term capital gain. Your gain is $80,000 − $50,000 = $30,000. Assume your taxable income puts you in the 15% long-term capital gains bracket and you don’t trigger NIIT. Federal tax owed is $30,000 × 15% = $4,500.
After a $10 broker fee and no state tax (assuming you live in a no-tax state), your net proceeds are $80,000 − $10 − $4,500 = $75,490. If you had sold in December 2023 (short-term, held less than one year) and faced a 24% ordinary income rate, your tax would be $30,000 × 24% = $7,200, and net proceeds would drop to $72,790.
- Purchase price: $50,000
- Sale price: $80,000
- Gain: $30,000
- Tax (long-term 15%): $4,500
- Net proceeds: $75,490
Example 3: Rental Property with Depreciation Recapture
You bought a rental property in 2015 for $300,000, spent $20,000 on capital improvements, and took $40,000 in depreciation deductions over ten years. Your adjusted basis is $300,000 + $20,000 − $40,000 = $280,000. You sold the property in 2025 for $500,000 and paid $30,000 in selling costs (commission and closing). Your capital gain is $500,000 − $30,000 − $280,000 = $190,000.
The IRS recaptures the $40,000 depreciation at up to 25%, so recapture tax is $40,000 × 25% = $10,000. The remaining $150,000 gain is taxed at the long-term rate of 15% = $22,500. Total federal tax is $10,000 + $22,500 = $32,500. Assuming a 5% state tax on the full $190,000 gain ($9,500), your total tax is $42,000, and net proceeds are approximately $500,000 − $30,000 − $42,000 = $428,000 before mortgage payoff.
- Purchase price: $300,000
- Improvements: $20,000
- Accumulated depreciation: $40,000
- Adjusted basis: $280,000
- Gain: $190,000 (of which $40,000 is recaptured depreciation)
- Total tax (federal + state): $42,000
- Net proceeds: $428,000
Using Spreadsheets and Online Calculators to Estimate After-Tax Proceeds
Online capital gains calculators ask for a handful of inputs: sale price, purchase price (or adjusted basis), capital improvements, holding period (short-term or long-term), federal filing status, state of residence, and selling expenses. The calculator applies current-year tax brackets, adds NIIT if your income crosses the threshold, and outputs estimated federal tax, state tax, and net proceeds.
These tools are fast for simple sales but can miss nuances like depreciation recapture, specific identification of cost basis for securities, or multi-state tax rules. Use them for ballpark estimates, then verify with your own spreadsheet or tax advisor before listing the asset.
A spreadsheet gives you full control and transparency. Set up columns for every input and formula so you can adjust assumptions and instantly see how changes in sale price, timing, or deductions affect your net proceeds. Label rows clearly and use cell references instead of hardcoded numbers so you can reuse the template for future sales. Save a copy with your actual receipts and closing statements as backup documentation for your tax return.
Essential spreadsheet columns to include:
- A: Sale Price: contract amount or final transaction value.
- B: Purchase Price: what you originally paid.
- C: Capital Improvements: sum of all receipts for improvements.
- D: Accumulated Depreciation: total depreciation claimed (if applicable).
- E: Adjusted Basis: formula
=B + C − D. - F: Selling Costs: commissions, closing costs, transfer taxes, fees.
- G: Capital Gain: formula
=A − F − E. - H: Exclusions: primary residence exclusion ($250,000 or $500,000) if eligible.
- I: Taxable Gain: formula
=MAX(G − H, 0). - J: Federal Tax Rate: select short-term or long-term rate based on holding period and income bracket.
- K: Federal Tax: formula
=I × J. - L: State Tax Rate: your state’s capital gains rate.
- M: State Tax: formula
=I × L. - N: NIIT: formula
=IF(your MAGI > threshold, I × 0.038, 0). - O: Depreciation Recapture Tax: if rental property,
=depreciation amount × 0.25. - P: Net Proceeds: formula
=A − F − K − M − N − O − mortgage payoff − other fees.
Tax-Reduction Strategies to Lower Capital Gains Before You Sell
Smart timing and planning can save thousands in taxes without changing the sale price. Start evaluating these strategies months before you list, not days.
First, review your holding period. If you’re close to the one-year mark, wait until you cross it to convert short-term gains (taxed up to 37%) into long-term gains (taxed at 0%, 15%, or 20%). Selling one day too early can double your effective tax rate. For example, a $100,000 short-term gain at a 32% ordinary rate costs $32,000 in federal tax, but the same gain held one more day and taxed at 15% long-term costs $15,000. That’s a $17,000 savings.
Primary Residence Exclusion
If you meet the ownership and use tests, you can exclude up to $250,000 of gain as a single filer or $500,000 as married filing jointly. You must have owned the home for at least 2 of the last 5 years and used it as your main home for at least 2 of the last 5 years. You can’t have used the exclusion on another home sale in the prior 2 years. Exceptions exist for certain military, foreign service, or health-related moves.
Example: buy for $400,000, sell for $700,000, raw gain $300,000. Single filer excludes $250,000, leaving $50,000 taxable. Married filers exclude the full $300,000 and owe zero tax.
Tax-Loss Harvesting
Realize capital losses in the same tax year to offset capital gains. If you have $50,000 of taxable gain and sell another investment at a $20,000 loss, your net taxable gain drops to $30,000. Capital losses first offset capital gains of the same type (short-term losses offset short-term gains, long-term losses offset long-term gains), then offset the opposite type, and you can deduct up to $3,000 of excess losses against ordinary income. Remaining losses carry forward indefinitely.
Watch the wash-sale rule. If you repurchase the same or substantially identical security within 30 days before or after the loss sale, the loss is disallowed and added to the basis of the new shares.
1031 Exchange (Investment and Business Real Estate Only)
Defer capital gains on investment or business real estate by reinvesting proceeds into a like-kind replacement property under Internal Revenue Code Section 1031. You must identify the replacement property within 45 days of the sale closing and complete the purchase within 180 days. A qualified intermediary holds the proceeds (you can’t touch the cash).
The cost basis of the original property carries forward to the new property, so taxes are deferred, not eliminated. Example: sell rental property with $250,000 gain, complete 1031 into a new rental, owe zero tax now. When you eventually sell the new property without doing another exchange, you’ll pay tax on the accumulated gain from both properties.
Installment Sale
Spread the recognition of gain over multiple years by receiving sale proceeds in installments. Each payment includes a portion of gain, taxed in the year received. This strategy can keep you in lower tax brackets each year instead of triggering a large one-time gain. It requires trust in the buyer’s ability to pay and careful structuring with legal and tax advice. Installment sales work best for private sales of real estate or business assets, not publicly traded securities.
Preventing Future Miscalculations of Capital Gains and Net Proceeds
Build a system now so you never scramble for missing receipts or guess at your basis again. Keep a dedicated folder (physical or digital) for every asset you own. File purchase contracts, closing statements, improvement invoices, depreciation schedules, brokerage confirmations, and dividend reinvestment records as soon as you get them.
Update your records annually, especially after tax season when you’ve documented depreciation or reinvested dividends. Use a simple spreadsheet to track purchase price, date acquired, improvements, depreciation taken, and current estimated value for each asset. When you’re ready to sell, you’ll have every number you need in one place.
Seven prevention steps to follow:
- Save all purchase and sale documents: contracts, settlement statements, brokerage confirmations, closing disclosures.
- Track and receipt every capital improvement: new roof, HVAC, kitchen remodel, room addition, paving, landscaping that adds value.
- Separate capital improvements from routine repairs: repairs (painting, fixing a leak) don’t increase basis; improvements do.
- Maintain a depreciation schedule: if you rent the property or use it in business, track accumulated depreciation annually.
- Record reinvested dividends and stock splits: these increase your basis in securities and reduce taxable gain.
- Verify current-year tax brackets and rates: federal long-term and short-term brackets, NIIT thresholds, and state rates change; check IRS.gov and your state department of revenue before calculating.
- Run a test calculation months before listing: use the spreadsheet template and realistic sale price estimates to see whether timing or improvements can lower your tax bill.
When to Get Professional Help Before Selling an Asset
Hire a CPA or enrolled agent when your sale involves depreciation recapture, multi-state tax exposure, large gains that push you into higher brackets or trigger NIIT, or complex cost-basis questions (inherited property, gifted property, stock options, cryptocurrency). Tax professionals calculate adjusted basis using your actual records, apply current-year rules for recapture and exclusions, estimate your total tax bill including state and local taxes, and advise on timing strategies like holding longer or spreading sales across tax years.
They also prepare or review Schedule D (Capital Gains and Losses) and Form 8949 (Sales and Other Dispositions of Capital Assets) to ensure your return matches broker and escrow company reporting.
If you plan to use a 1031 exchange, installment sale, or charitable remainder trust, consult a tax advisor and real estate attorney before listing. These strategies require strict compliance with IRS rules and tight deadlines. Mistakes can disqualify the deferral and trigger immediate tax. For high-value sales (gains over $100,000), multi-asset transactions (selling a business with real estate, equipment, and goodwill), or sales that span multiple states (rental property in one state, primary residence in another), professional guidance usually saves more in taxes than it costs in fees.
Four documents to gather and bring to your tax professional before the sale:
- Original purchase documents: contract, settlement statement, or brokerage confirmation showing purchase price and date.
- Improvement receipts and invoices: itemized bills for capital improvements with dates and amounts paid.
- Depreciation schedules: tax returns or worksheets showing annual depreciation claimed on rental or business property.
- Estimated sale contract or listing price: draft purchase agreement or realistic market value to model tax scenarios.
Final Words
You can now use the exact formulas and quick checks from this post to turn a gross sale price into the cash you’ll actually receive.
We defined capital gains and adjusted basis, showed why estimates get tricky, walked through step‑by‑step calculations, net‑proceeds math, worked examples, spreadsheets, tax‑reduction moves, recordkeeping, and when to get professional help.
Before you list, run the numbers with the how to calculate estimated capital gains tax and net proceeds before selling an asset steps here — it cuts surprises and helps you keep more of the sale.
FAQ
Q: How do I calculate estimated capital gains tax and net proceeds before selling an asset?
A: The estimated capital gains tax and net proceeds before selling are found by: capital gain = sale price − adjusted basis; tax = gain × applicable rate(s); net proceeds = sale price − selling costs − taxes.
Q: What is adjusted cost basis and how do I compute it?
A: The adjusted cost basis is the purchase price adjusted for improvements and depreciation; compute it as purchase price + capitalized improvements − accumulated depreciation (plus any capitalized fees).
Q: How do I know if my gain is short-term or long-term and why it matters?
A: Whether a gain is short-term or long-term depends on holding period: more than one year is long-term; this matters because long-term rates are usually lower than ordinary income rates.
Q: What inputs do I need to estimate capital gains tax and net proceeds?
A: The inputs you need are sale price, adjusted cost basis, selling costs (commissions/closing fees), federal and state tax rates (and NIIT), plus any transfer or other fees.
Q: How do I calculate net proceeds before a sale?
A: Net proceeds before a sale equal sale price minus commissions, closing costs, transfer fees, and estimated federal/state taxes (including NIIT); estimate taxes on the taxable gain first, then subtract all costs.
Q: Why is estimating capital gains tax and net proceeds complicated?
A: Estimating is complicated because basis adjustments, depreciation recapture, varying federal/state tax rates, and selling expenses all change the taxable gain and final cash you receive.
Q: What step-by-step actions should I take before selling an asset?
A: Before selling, gather purchase and improvement records, compute adjusted basis, estimate sale proceeds minus fees, check holding period, apply tax rates (federal/NIIT/state), then calculate taxes and net proceeds.
Q: What are common calculation mistakes to avoid?
A: Common mistakes include forgetting improvements or depreciation, ignoring state tax or NIIT, misclassifying holding period, and overlooking commissions, closing costs, or transfer taxes.
Q: Can spreadsheets or online calculators help estimate after-tax proceeds, and what inputs do they need?
A: Spreadsheets and calculators can help; they require sale price, basis, holding period, commissions, federal/state tax rates, NIIT, and other fees—set columns for each to automate the math.
Q: What tax-reduction strategies can lower capital gains before selling?
A: Strategies to lower capital gains include holding over a year for LTCG rates, tax-loss harvesting, primary residence exclusion, 1031 exchanges for real estate, installment sales, and charitable gifting.
Q: What records should I keep to prevent future miscalculations?
A: Keep purchase records, receipts for improvements, closing statements, depreciation schedules, trade histories, dividend reinvestment records, and prior tax returns to support basis and adjustments.
Q: When should I get professional help before selling and what documents should I bring?
A: Get help if the sale is large, involves depreciation recapture, multi-state issues, NIIT, or complex ownership. Bring purchase records, improvement receipts, depreciation schedules, and sale closing statements.

